Why Do Singapore Contractors Lose Up to 12% Margin to Project Cost Overruns?
A Singapore contractor closes the margin gap on project cost overruns by tracking four specific leakage points in real time: material over-ordering and site waste, labour cost drift between tendering estimates and actual hours, subcontractor claims and variations arriving without formal review, and progress billing that lags behind completed work. The most common financial surprise in construction and contracting isn’t a client who doesn’t pay – it’s discovering, three-quarters of the way through a project, that 90% of the budget is spent with 40% of the work still left. By the time that’s visible, the options are limited: absorb the loss, chase a variation claim after the fact, or cut quality.
Job costing problems don’t start when a project goes over budget. They start when the project is priced without accurate historical cost data, when material consumption isn’t tracked against budget in real time, and when labour costs are reconciled monthly rather than daily. By the time a project manager realises there’s a problem, the damage is already done. Below is exactly where that margin disappears, what real-time job costing needs to do about it, and how a connected platform closes the gap.
Where Does Project Margin Actually Disappear?
In the same four places, consistently, across construction, electrical, M&E, and facility management contractors. Material over-ordering and site waste, labour cost drift that’s invisible until payroll, subcontractor claims and variations arriving without formal tracking, and progress billing that lags behind completed work. None of these show up as a single dramatic failure – each one leaks a few percentage points quietly, and by the time all four are added together at project close, the margin that looked healthy at tender has largely evaporated.
Material Over-Ordering and Waste
Without real-time material consumption tracking against project budgets, procurement teams order conservatively to avoid shortages. The result is systematic over-ordering: materials not needed for this project end up in the yard, depreciate, and are eventually written off. For projects with high material content – structural works, electrical installations, HVAC systems – this over-ordering can represent 5-8% of project cost above budget. Site waste compounds it: when materials aren’t signed out against specific job orders, consumption is invisible, and the variance only surfaces at project end during final reconciliation, too late to act on.
Labour Cost Drift
Project labour budgets are set at tendering stage based on estimated man-days. When actual hours are tracked only at payroll – weekly or monthly – the gap between budgeted and actual labour cost is invisible until it’s unrecoverable. Jobs scheduled for 20 man-days consume 28 without anyone triggering a review. Overtime is a particular problem: workers staying late to meet a milestone generate costs that don’t appear in the job budget, don’t get allocated to the specific job, and don’t trigger an alert – they show up in monthly payroll as a variance with no job-level explanation.
Subcontractor Cost Management
Projects relying on subcontractors face an additional cost control layer. Subcontractor progress claims arrive on their schedule, not yours. Variation orders accumulate without formal approval. When a subcontractor’s final account comes in significantly above the contract sum, that conversation happens after the work is done and your leverage is gone. Real-time tracking of commitments, approved variations, and progress claims against the contract sum means the project manager knows the projected final cost, not just what’s been invoiced so far.
Invoicing Delays and Cash Flow Impact
Progress billing should be mechanical. Without a system tracking work completion against billing milestones, invoices go out late or miss recovery of approved variations. Each billing delay costs working capital – a project billed 30 days late throughout its duration is effectively an interest-free loan to the client for the entire project period.
What Real-Time Job Costing Actually Needs to Do
Real-Time Cost Dashboard: Planned vs. Actual
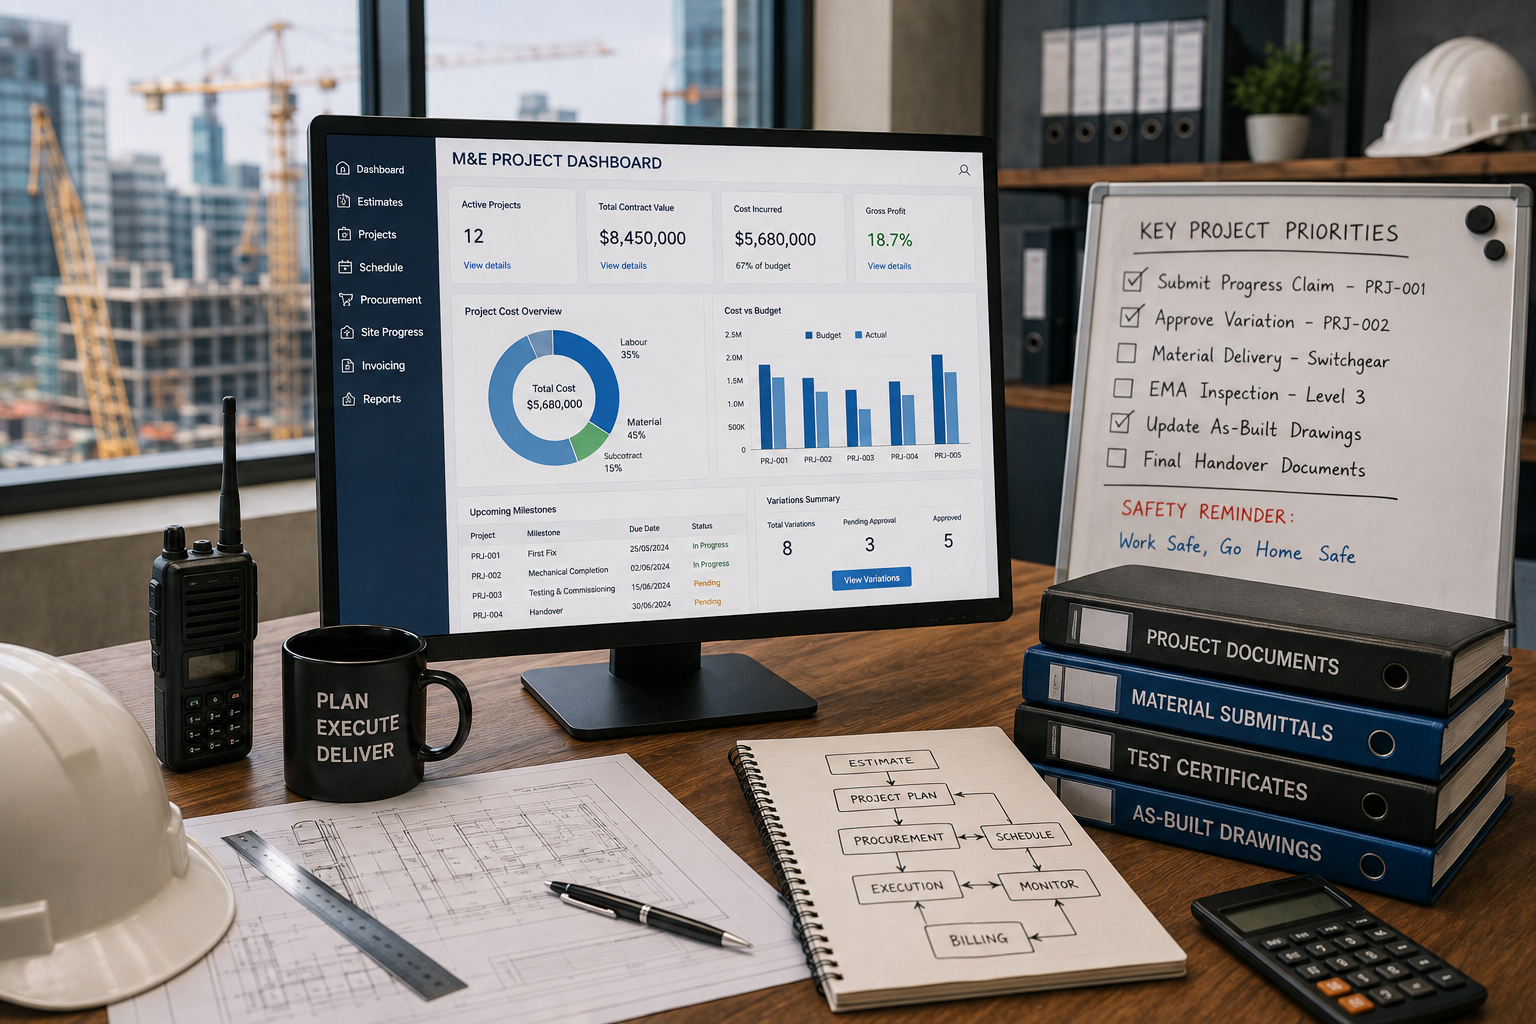
The central tool is the planned vs. actual comparison, visible by project at any point. Cost categories – materials, labour, subcontractors, equipment, overheads – are tracked against budget in real time, so a project showing 65% budget consumed at 50% completion is flagged immediately, while there’s still time to investigate and correct it. This requires costs to be recorded against job orders as they’re incurred: material issues at the point of issue, timesheets submitted and approved daily, subcontractor claims recorded the moment they’re received. Monthly reconciliation doesn’t give real-time control on active projects.
Material Planning and Consumption Monitoring
A material plan is created for each project at the start – materials required, quantities, cost per unit, total budget – and as materials are issued from the warehouse to site, consumption is recorded against the project. When consumption runs ahead of plan, the early alert gives time to investigate whether it’s measurement error, waste, theft, or a genuine scope change needing formalisation, so waste is quantified rather than silently absorbed into cost.
Progress Billing and Change Order Management
Billing milestones defined at project start are tracked against actual progress, and a completed milestone generates the invoice, or flags it for review before sending. Approved variation orders track from submission through client approval, then flow into the revised budget and billing schedule automatically. Every approved variation has a cost implication recorded in both the project budget and the billing schedule, so nothing that should be billed to the client gets silently absorbed as a project cost instead.
Subcontractor Order Management
Subcontractor orders are created against specific job orders with defined scope, contract sum, and payment milestones. Progress claims are recorded against the subcontract and reviewed against agreed milestones before approval, with variation orders tracked separately from the original contract sum – so at any point, the committed cost, approved variations, amount paid, and projected final account are all known, not just the invoices received so far.
Historical Data for Better Tendering
A complete job costing system reports profitability at every level – per project, per project type, per customer segment, and across the portfolio. Over time this historical data becomes the most reliable input to competitive tendering: prices reflect what similar jobs actually cost, not optimistic estimates. Knowing that electrical installation jobs for commercial buildings consistently run 8% over labour budget tells you exactly where to build margin into the next tender, or where to investigate process inefficiency.
How Moxogo Connects Job Costing to the Rest of the Business
Moxogo’s Job Costing & Budgeting solution treats job costing as the centre of a connected engine rather than a standalone module bolted onto accounting. Bid opportunities and client interactions are captured in CRM from first contact, so a quote is already linked to the customer profile before the job exists. A successful bid converts instantly into an active job budget through Sales Management, with full visibility into how contract terms and change orders affect final project margins.
From there, Purchase Management controls material costs at the source – purchase orders and vendor bills are tracked against estimated costs before an overrun happens, not after. Inventory & Warehouse allocates material cost directly to the specific project and monitors consumption against planned quantities, which is what makes material waste visible in real time instead of at final reconciliation. On the billing side, Invoicing Management monitors total contract value, tracks invoiced and paid amounts, and auto-updates outstanding dues, so progress billing doesn’t lag behind completed work. Project Management keeps field teams and financial data in sync, scheduling tasks and tracking labour hours so every man-hour is accounted for in the job cost report.
At the job level, this shows up as Job Cost Sheets that break down every job order into materials, labour, and overhead lines with planned quantity, cost per unit, and actual purchase or vendor bill quantity side by side, so a variance is visible line by line, not just as a total. Job Orders, Subcontractor Orders, and Work Packages group the work in the way it’s actually delivered on site; Material Planning and Purchase Requisitions convert a project’s material needs directly into cost sheets or stock requests without manual re-keying.
The Results Singapore Contractors Are Reporting
Across the capabilities above, Moxogo’s own benchmark data shows a consistent pattern: real-time cost control typically delivers a 10-20% reduction in project overruns, data-driven bidding on historical job costing data improves gross margins by 5-10%, built-in quality control cuts rework-related costs by up to 30%, and tracking planned versus actual labour hours lifts workforce productivity by 10-15%.
One Singapore-based electrical and services company – providing M&E, mixed construction, and maintenance services since 1998 – reported the following after deploying Moxogo’s job costing suite:
- 12% margin recovery: the combination of reduced material waste, tighter labour tracking, and complete variation recovery, all previously invisible losses, recovers margin that was always theoretically available but being eroded by untracked costs.
- 40% reduction in admin time: eliminating manual compilation of project cost reports, reconciliation of materials across spreadsheets, and chasing of timesheet approvals frees up project manager time for actual project management.
- 98% budget accuracy: when costs are tracked in real time, the project’s projected final cost is accurate throughout its duration rather than being a best guess from last month’s partial data.
Implementation for Singapore Contracting Businesses
For contracting businesses implementing job costing ERP, the configuration centres on defining the cost structure: how projects are broken down into cost categories, how materials are coded, how labour is classified, and how overhead is allocated to projects. Getting this right before go-live is the single most important factor in whether the system produces useful management information from day one.
Most businesses find this configuration exercise surfaces inconsistencies in how costs have been classified historically – different project managers using different category names for the same cost, overhead allocation methods that don’t reflect actual consumption. Standardising the cost structure is itself a valuable management exercise, independent of the software. The practical go-live sequence starts with new projects rather than attempting to bring historical projects into the new system, avoiding the complexity of reconciling in-progress work and letting the team learn the system on projects where they have full control from the start.
Five Signals That It’s Time to Invest in Job Costing Software
- Projects regularly come in over budget and the cause isn’t identified until completion
- Variation claims are missed or submitted late because there’s no system tracking approved scope changes against billing
- Preparing a monthly project cost report requires more than two hours of manual data compilation
- Material consumption per project isn’t tracked – what was ordered is known, but not what was actually used
- Labour hours are reconciled monthly rather than tracked daily against project budgets
Any one of these justifies the investment. Most businesses that look honestly at their project cost management find two or three applying simultaneously.
Frequently Asked Questions
Why do Singapore contractors lose margin even on projects that look profitable at tender stage? Because the four leakage points, material over-ordering, labour cost drift, unmanaged subcontractor variations, and delayed progress billing, are invisible month to month and only surface in full at project close, by which point the margin is already gone.
How much margin can real-time job costing typically recover? Benchmark data shows a 10-20% reduction in project overruns and 5-10% improvement in gross margins from data-driven bidding; one Singapore M&E and construction client reported 12% margin recovery specifically from closing these tracking gaps.
What is the difference between tracking costs monthly and tracking them in real time? Monthly reconciliation shows a variance after it’s already unrecoverable. Real-time tracking flags a project running at 65% budget consumed against 50% completion immediately, while there’s still time to investigate and act.
Does job costing software replace the need for separate procurement, HR, and inventory systems? No, it depends on them being connected. Job costing is only as real-time as the systems feeding it: purchase orders, approved timesheets, and material issues need to flow into the job cost dashboard automatically rather than being reconciled manually across separate tools.
How should a contracting business sequence its go-live on job costing ERP? Start with new projects rather than migrating in-progress work. This avoids the complexity of reconciling active projects mid-stream and lets the team learn the system on jobs where they have full control from day one.
Next step: Moxogo’s Job Costing and Budgeting solution is built for Singapore contractors in construction, electrical, M&E, facility management, and professional services, connecting CRM, procurement, inventory, HR, and accounting to real-time project cost tracking in a single platform. Learn more about Moxogo Job Costing and Budgeting.
More Articles
The Resource Master Audit: Why ERP Rollouts Fail at the Data Layer, Not the Software Layer
Most ERP go-lives don’t fail on features. They fail on messy master data. Here’s the Resource Master Audit that prevents it.
Read Article
The Compounding Moat: How Operational Discipline Becomes a Brand Competitors Can’t Copy
Taglines get copied overnight. Clean operational data doesn’t. How operational discipline becomes an unassailable competitive moat for SMEs. ...
Read Article
Engine and Brakes: What the Global AI Safety Debate Means for Your Business
A recurring metaphor in the global AI safety conversation, a powerful engine paired with good brakes, turns out to describe SME AI adoption just as we...
Read Article